Executive Summary
- The standard S&P 500 weights each company by float-adjusted market capitalization, so the largest companies carry the most weight.
- The S&P 500 Equal Weight Index holds the same companies at a target of about 0.2% each, reset every quarter.
- Equal weight reduces reliance on the biggest companies and puts more money in the index's smaller constituents and in sectors with more members.
- The quarterly reset trims recent relative winners and adds to laggards by rule, which can raise turnover and add trading costs and taxable distributions.
- Neither method is lower risk by default. Both are stock indexes that can suffer substantial losses.
- Compare funds on expense ratio, turnover and tracking difference, and pick a weighting rule you can hold through periods when it lags.
You can own an S&P 500 fund and still have a large part of your money riding on a small group of companies. Owning hundreds of stocks tells you how many names are in the portfolio. The percentage invested in each one tells you how much those names matter.
The standard S&P 500 gives larger companies more weight. Its equal-weight counterpart gives each company approximately the same allocation at each quarterly reset. Both hold U.S. large-cap stocks, but they make different bets about how to spread your money. Equal weight reduces reliance on the largest companies while adding other risks, costs and reasons to lag the standard index.
How weighting works
The standard S&P 500 is weighted by float-adjusted market capitalization. Market capitalization is share price multiplied by shares outstanding. The float adjustment focuses on shares available to public investors, rather than all shares a company has issued. A company with more public market value generally receives a larger index weight.
The S&P 500 Equal Weight Index uses the same constituent companies. Each company receives a target weight of about 0.2% at a quarterly rebalance. Companies with multiple share classes can have that company allocation split between share classes. The equal-weight target uses prices from an earlier reference date, so actual weights can already differ when a rebalance takes effect and continue to drift afterward.
An index is a set of rules and a calculation. You invest through a fund or another product that seeks to follow it. The fund's fees, implementation and trading costs can cause its return to differ from the index it tracks.
1. Compare the allocations
Weighting changes how much capital you put behind each company. A simplified example makes the difference easier to see than a list of 500 holdings.
Imagine a fictional five-company index with $100 billion of combined public market value. Company A represents $40 billion of that value, while Company E represents $8 billion. An illustrative $100,000 portfolio could allocate as follows, before fees and trading costs.
| Company | Market value | Market weight | Equal weight |
|---|---|---|---|
| A | $40 billion | $40,000 (40%) | $20,000 (20%) |
| B | $25 billion | $25,000 (25%) | $20,000 (20%) |
| C | $15 billion | $15,000 (15%) | $20,000 (20%) |
| D | $12 billion | $12,000 (12%) | $20,000 (20%) |
| E | $8 billion | $8,000 (8%) | $20,000 (20%) |
Fictional companies and market values. These are allocation calculations, not S&P 500 holdings, investment returns or recommendations.
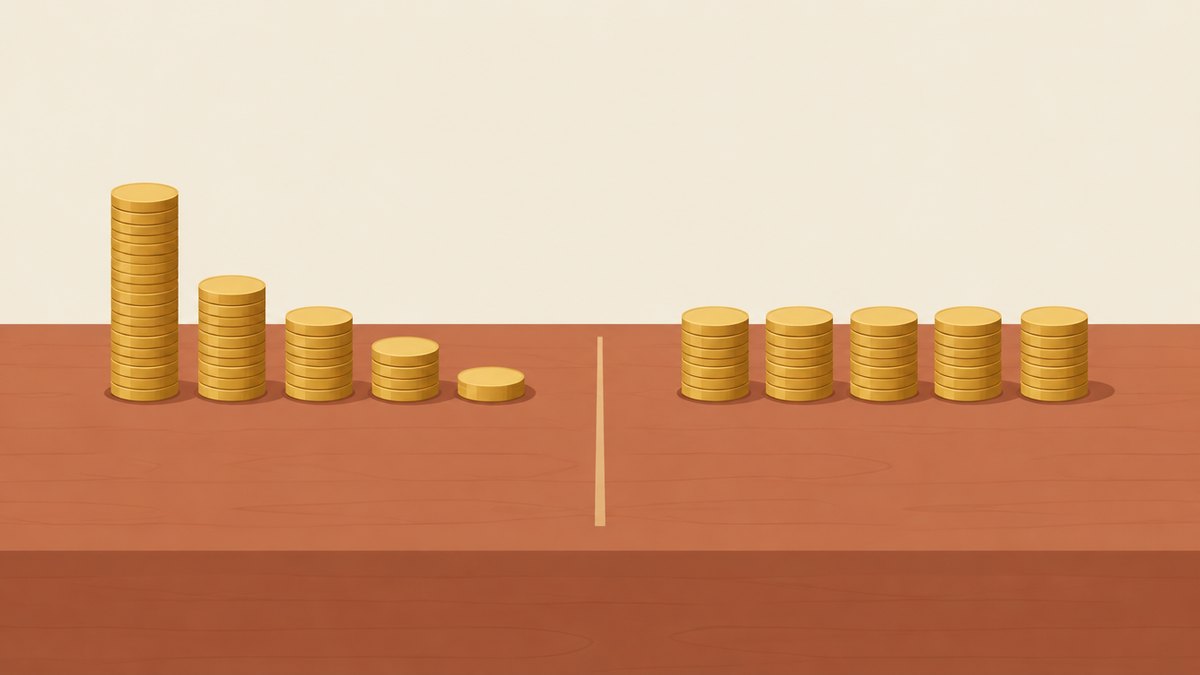
Both portfolios own all five companies. In the market-weight portfolio, A accounts for 40% of the allocation. In the equal-weight portfolio, it accounts for 20%. Meanwhile, the allocation to E increases from 8% to 20%.
Equal weighting redistributes exposure. It reduces the influence of the biggest companies by giving more influence to the smaller companies already in the index. That trade can help or hurt. It does not make every company equally profitable, equally valuable or equally risky.
2. Understand rebalancing
A market-weight index allows relative price changes to alter its weights. If one constituent's price rises faster than the others, its market value and its share of the index generally increase. That price movement alone does not require a fund tracking the index to sell the stock to restore its old percentage.
Equal weighting has a different maintenance rule. At the quarterly reset, it brings company weights back toward the equal-weight target. That generally means reducing positions that have grown above their targets and adding to positions that have fallen below them. Membership changes and other index adjustments can also require trading under either approach.
This creates a systematic tilt away from recent relative winners at rebalance. It is a mechanical rule, not a judgment that the winners are overvalued or that the laggards are about to recover.
When leadership broadens beyond the largest companies, the additional exposure to other constituents may help equal weight. When a small group of very large companies keeps leading, the smaller allocations to those companies may hold it back. Neither observation tells you which environment comes next.
3. Check the exposures
Equal weighting changes more than the top ten holdings. It also changes the portfolio's exposure to sectors and to the smaller companies within the S&P 500. Those are meaningful differences in an investment portfolio, even when the holdings list looks familiar.
An equal-weight index does not give every sector an equal allocation. A sector with more constituent companies has a larger combined target weight than one with fewer companies. In a hypothetical 500-company index, 50 companies with 0.2% targets would give their sector a 10% combined target. A sector with 25 companies would have a 5% combined target. Actual weights can differ as prices move. These are arithmetic examples, not current sector weights.
Equal weight also puts more money into the S&P 500's smaller constituents relative to market weight. They are still members of a large-cap index. This is not the same exposure as buying a small-cap fund. The approach can also introduce size, value and rebalancing-related tilts, which affect how it behaves.
Less exposure to the largest companies does not establish lower overall risk. Both versions remain stock indexes and can suffer substantial losses. A portfolio's risk also depends on the businesses it owns, their valuations, how their prices move together and the other investments alongside them.
4. Compare the funds
An appealing index methodology can be expensive to implement. Compare the actual fund's expense ratio, trading costs and record of tracking its own benchmark. A tracking difference measures how far a fund's return differs from its index. The difference between the equal-weight and market-weight indexes is a separate question about the exposures you chose.
For an expense-ratio illustration, assume two funds charge 0.20% and 0.03% annually. Applied to an unchanged $100,000 balance, those rates represent about $200 and $30 a year, respectively. The roughly $170 difference is a cost comparison using assumed rates, not a quote for particular funds or a forecast of what either investment could earn.
Quarterly resets can create more turnover than allowing market weights to move with prices. Turnover can add trading costs and, in a taxable fund, may contribute to capital-gain distributions. ETF structure and a manager's implementation can affect the result. Equal weight does not automatically mean a large tax bill, just as an ETF label does not guarantee none. Read the fund's prospectus, expenses and tax information before comparing products.
5. Choose your approach
The investment case for equal weight is a deliberate preference for spreading capital more evenly across the S&P 500's companies. Its case should include a willingness to own more of the smaller constituents, rebalance on schedule and accept periods when that approach falls behind market weight.
The case for market weight is a preference for owning companies in proportion to their public market values, with greater influence from the largest businesses. Its case should include a willingness to accept the concentration that can build when those companies become a larger share of the market.
Our Q3 market recap looks at changes in market leadership. A weighting decision should survive more than one quarter's leadership change. Review each approach against its own purpose and benchmark, rather than treating recent relative performance as an instruction to switch.
| Feature | Market weight | Equal weight |
|---|---|---|
| Starting allocation | Public market value | Approximately equal per company |
| Largest companies | More influence | Less influence at the reset |
| Smaller constituents | Less influence | More influence |
| Relative price changes | Weights generally drift with market values | Quarterly resets toward equal weights |
| Main trade-off | Greater concentration can develop | Different exposures and additional rebalancing |
| Fund selection | Check costs and tracking | Check costs, turnover and tracking |
Before choosing a fund, write down which weighting rule you want, what you expect it to change and what evidence would make you reconsider. A different label on the fund is useful only if you understand the different portfolio underneath it.
Disclosures: The information provided is for educational and informational purposes only and does not constitute investment, tax, or legal advice and should not be relied on as such. It is not a solicitation to buy or an offer to sell any security. It does not take into account any individual's particular investment objectives, financial situation, or needs. You should consult your own financial advisor, tax advisor, or attorney before acting on any information herein. All investing involves risk, including the possible loss of principal. Figures and tax limits referenced are for the applicable tax year and are subject to change. Valence Wealth, LLC is a registered investment advisor in the State of Arizona. Registration does not imply any specific level of skill or training.
Indexes are unmanaged, cannot be invested in directly and do not include fund expenses. The allocation and fee examples are hypothetical illustrations, not actual holdings, investment performance or recommendations. Neither weighting method guarantees a profit or protects against loss. S&P 500 and S&P 500 Equal Weight are third-party indexes.
Sources
- S&P 500 Equal Weight IndexS&P Dow Jones Indices
- S&P U.S. Indices MethodologyS&P Dow Jones Indices
- S&P 500 Equal Weight Index FAQ, April 20, 2026S&P Dow Jones Indices
- Outperformance in Equal-Weight Indices, January 2018, methodology and factor discussion onlyS&P Dow Jones Indices
- Index FundsU.S. Securities and Exchange Commission
- Exchange-Traded Funds (ETFs)U.S. Securities and Exchange Commission