Executive Summary
- Net unrealized appreciation (NUA) is the growth in your employer's stock inside a 401(k), above what the plan paid for it. Take the shares out as shares in a lump-sum distribution, and the plan's cost basis is taxed as ordinary income that year, while the NUA is taxed as long-term capital gain when you sell.
- An exchange fund, sometimes called a swap fund, is a private partnership that pools stock from many investors. Contributing shares to one generally doesn't trigger tax on the gain.
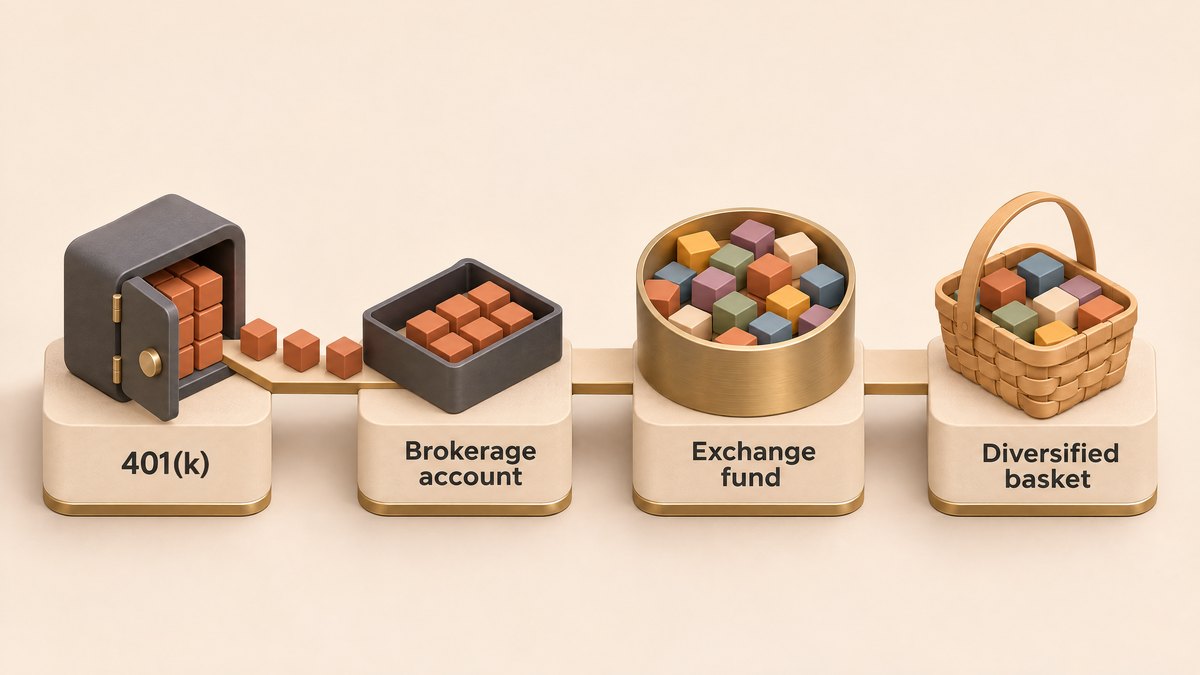
- You can take employer stock out of a 401(k) under the NUA rules, then contribute it to an exchange fund to diversify without selling, so the capital gains tax on the NUA stays deferred. The shares have to go to a taxable account first, because shares rolled into an IRA lose NUA treatment.
- The exchange fund generally postpones the tax on the NUA until you sell. Your cost basis carries into the exchange fund and on to the stocks you get back.
- Exchange funds generally require accredited investor or qualified purchaser status, lock up your money for about seven years and charge annual fees. Many employers prohibit the use of exchange funds with company stock for some or all employees, so check your stock plan and insider trading policy before participating.
How NUA and an exchange fund fit together
If you've spent years at one company, a big part of your 401(k) may be its stock, bought long ago at much lower prices. Roll the account into an IRA when you leave and you can diversify inside the IRA without tax, but every dollar, growth included, is taxed as ordinary income when you withdraw it.
Our video Before You Retire With Company Stock, Check These 3 Things shows what a large position in one stock can do to a retirement plan.
There's another option, and it takes two steps:
- Take the company shares out of the plan as shares, in a lump-sum distribution. Under the NUA rules, only what the plan paid for them is taxed now, as ordinary income, and the growth above that is taxed as long-term capital gain when you sell.
- Once the shares are in a taxable brokerage account, you can generally contribute them to an exchange fund without triggering tax on the NUA. After about seven years you can take out a basket of different stocks.
The second step is where the exchange fund can add value. After an NUA distribution, you could diversify by selling the shares, which triggers the capital gains tax on the NUA. Contributing them to an exchange fund instead lets you diversify while that tax stays deferred.
The order matters. Shares rolled into an IRA lose NUA treatment, so the stock has to go to a taxable account before it can go into an exchange fund.
This guide covers employer stock in the pre-tax part of a 401(k) or similar qualified plan, and federal taxes. NUA applies only to employer stock held inside the plan.
| Step | What happens | Tax now | Tax later |
|---|---|---|---|
| In-kind lump-sum distribution | Company shares move from the 401(k) to a taxable brokerage account | Ordinary income on the plan's cost basis | NUA taxed as long-term gain when you sell |
| Exchange fund contribution | The shares go into a partnership for an interest in a pooled portfolio | None | The gain carries over in your basis |
| Exit after about seven years | You can take a basket of stocks in kind | Depends on how the exchange fund is set up | Gain taxed when you sell the stocks |
1. NUA
Most money in a pre-tax 401(k) is taxed as ordinary income when it comes out. Section 402(e)(4) of the tax code makes an exception for your employer's stock. If the shares come out as shares (an in-kind distribution) in a lump-sum distribution, their value splits into three pieces, as IRS Publication 575 explains.
- The cost basis. What the plan paid for the shares is taxed as ordinary income in the year of the distribution.
- The NUA. The growth above that cost isn't taxed until you sell. Then it's long-term capital gain, even if you sell the next day.
- Later growth. Any rise after the distribution is a capital gain too, and it's long-term only if you hold the shares for more than a year after the distribution.
When you sell NUA shares you hold directly, the NUA part of the gain is also exempt from the 3.8% net investment income tax (NIIT).
2. Lump-sum rules
NUA treatment is easy to lose, and once the shares land in an IRA it's gone. Section 402(e)(4) sets four requirements.
- A triggering event. For an employee, the payout has to come after you reach age 59½, or because you left your job (separation from service) or died. Disability counts only for the self-employed.
- The whole balance, in one tax year. Everything to your credit in the plan has to be paid out within a single tax year. The rest of the account can generally be rolled into an IRA in that same year, while the company shares go to a taxable account.
- Every plan of the same type. All of an employer's plans of the same type as your 401(k), which is generally a profit-sharing or stock bonus plan, count as one plan, so each of them has to be emptied in that same tax year. A pension plan is generally a different type, so it doesn't have to be paid out.
- Shares, not cash. The employer stock has to be distributed as shares.
The tax on the cost basis is due for the year of the distribution even if you don't sell a share, and a payout of shares alone may have little or no federal tax withheld. If you're under 59½, the 10% additional tax can also apply to the cost basis, though not to the NUA, unless an exception applies. One exception covers payouts after you leave your job in or after the year you turn 55.
3. The exchange fund
An exchange fund, sometimes called a swap fund, is a private partnership. You and other investors each contribute shares of a different company, and each of you receives an interest in the whole pool. Under Section 721, contributing property to a partnership in exchange for an interest in it generally isn't taxed.
Your cost basis comes along. Your interest in the exchange fund takes the same basis your shares had, which for NUA shares is the plan's cost basis.
Exchange funds are built around one exception. A contribution that diversifies you is taxed if the partnership would count as an investment company, which generally means more than 80% of its assets are marketable stocks and securities. So exchange funds hold part of their assets in something else, often real estate, and that slice is part of what you own.
The seven-year term comes from partnership tax rules. If the exchange fund passes your shares to another investor, or gives you other stocks, within seven years of your contribution, your gain is generally taxed. Leave early and exchange funds generally hand back the shares you contributed, so you're concentrated again after paying fees. After the term, you can generally take a basket of stocks out in kind, and the basket takes the basis of your exchange fund interest.
While you're in, you'll get a Schedule K-1 each year and owe tax on your share of the exchange fund's income, such as dividends, whether or not it's paid out to you.
Our exchange funds explainer covers the structure in more depth. Our video If I Had Too Much Company Stock, I'd Do These 4 Things compares an exchange fund with three other ways to unwind a concentrated position.
4. What carries through the exchange fund
The NUA generally isn't taxed when you contribute the shares. It stays inside your carried-over basis and is generally taxed when you sell the exchange fund interest or the stocks you get back. Holding periods carry too, so after seven years any gain is generally long-term anyway, and NUA's long-term-from-day-one rule adds little by then.
5. Exchange fund versus a sale
The real choice after an NUA distribution is between selling the shares and contributing them to an exchange fund. Selling diversifies you but triggers the capital gains tax on the NUA now. An exchange fund diversifies you while that tax stays deferred. Comparing NUA plus an exchange fund with an IRA rollover would credit the exchange fund with a benefit that comes from NUA itself.
Here's a hypothetical with round numbers. Your 401(k) holds $1,000,000 of company stock, and the plan's cost basis is $150,000, so the NUA is $850,000. You take the shares out in kind, and $150,000 is ordinary income this year. At an assumed 35% rate, that's roughly $52,500 of federal tax.
- Sell after the distribution. The $850,000 of NUA is long-term capital gain this year. At an assumed 20% rate, that's roughly $170,000 of federal tax now, with no 3.8% tax on the NUA. What's left is yours to invest however you like.
- Contribute to an exchange fund. That $170,000 isn't due now. Your $150,000 basis carries into the exchange fund, so the $850,000 of gain is still there, along with any later growth.
The illustration assumes the $52,500 is paid from other savings and leaves out state tax, exchange fund fees, investment returns and the 10% early-withdrawal tax. It's a hypothetical, not a projection.
Putting off a tax has value, because money that would have gone to the IRS stays invested. In the example, selling leaves about $830,000 to reinvest after the tax on the NUA, while the exchange fund keeps the full $1,000,000 invested in a diversified pool. That's the core of the strategy: you diversify away from one stock without paying the capital gains tax on the NUA now.
The trade-off is cost and commitment. An exchange fund charges fees every year you're in, which reduce the value of deferring the tax, and your money is generally committed for about seven years. The longer you'd hold the investments after the term and the lower the fees, the more the deferral can be worth.
You can also sell in stages over a few years, or sell and move the money into a direct-indexing account built to harvest losses. Our video on direct indexing covers that trade-off.
An exchange fund can fit when all of these are true:
- The cost basis is low compared with the shares' value.
- You won't need the money for at least seven years, and you'd likely hold the investments well after that.
- You qualify as an accredited investor or qualified purchaser, and an exchange fund will take your company's stock.
- Your company's trading policy allows it, or no longer applies to you.
- You're comfortable owning a pool built from other investors' stocks.
6. Costs and limits
Each step has its own costs, and the exchange fund adds more.
- A tax bill now. Ordinary income tax on the cost basis is due for the year of the distribution, and that income can push the rest of the year's income into a higher bracket. Our guide to safe harbor estimated taxes explains how to avoid an underpayment penalty when little is withheld.
- Lost IRA deferral. Inside an IRA, dividends and gains aren't taxed until you withdraw. In an exchange fund, your share of its income is taxed to you each year.
- The lock-up. Plan on about seven years. Leaving early generally returns your own shares.
- Fees. Exchange funds charge annual fees for the whole time you're in. Ask for the full schedule before you commit.
- Basket risk. You swap one stock for a share of whatever other investors contributed, plus the exchange fund's non-stock assets. You don't choose the mix, and it can lose value.
- Eligibility. Exchange funds are private offerings, generally limited to accredited investors, and some also require qualified purchasers. For an individual, accredited generally means a net worth over $1 million, not counting your home, or income over $200,000 ($300,000 with a spouse or partner) in each of the last two years with the same expected this year. A qualified purchaser generally owns at least $5 million in investments.
- Rules that can change. S.2095, a Senate bill introduced in June 2025, would tax contributions to exchange funds like these made after it became law. As of this writing, its latest listed action is referral to the Senate Finance Committee.
Trading policies. SEC rules require public companies to describe their policies on employees hedging company stock, and the rule names exchange funds as one example. Meta, Alphabet and Intel bar hedging for all employees. Meta and Intel name exchange funds among the barred transactions, and Alphabet listed them among barred hedging in 2023 and 2024. Amazon bars it for directors, executive officers and employees at Level 11 and above, and puts conditions on other employees.
These rules mainly apply while you work there, but some keep applying after you leave. Read your company's policy before you contribute. If you're still covered, a contribution may be barred or need approval. Our guides to Meta RSUs and Intel RSUs cover those companies' trading rules in more detail.
7. Check this before a rollover
The rollover paperwork is the point of no return for NUA, so these come first.
- Confirm the stock and its cost basis. Ask your plan administrator whether the plan holds company stock for you, and for its cost basis and NUA.
- Confirm the plan pays out shares. Ask whether it can send company stock as shares to a brokerage account while the rest goes to an IRA in the same year.
- Map the tax year. Plan the whole payout, including other plans of the same type, inside one tax year. If you've already taken money out since leaving or turning 59½, ask a tax professional whether NUA is still available.
- Line up the cash for the tax. Estimate the tax on the cost basis and where the money will come from.
- Read your trading policy, then vet the exchange fund. Check whether the policy bars exchange funds or still applies after you leave. Then confirm you qualify, that an exchange fund will take your stock, and its fees, term and early-exit terms.
- Run three paths side by side. With a tax professional, compare an IRA rollover, NUA with a sale, and NUA with an exchange fund, using your own basis, tax rates and time horizon.
This is general education, not a recommendation. Whether NUA or an exchange fund fits depends on your cost basis, tax rates now and later, time horizon, cash needs, eligibility, company policies and goals. We found no IRS guidance on whether NUA's exemption from the 3.8% NIIT, or its treatment at death, carries into an exchange fund, so confirm your position with a tax professional before acting. The dollar figures are a hypothetical illustration, not a projection or a result. Plan rules, exchange fund terms and tax law can change.
Disclosures: The information provided is for educational and informational purposes only and does not constitute investment, tax, or legal advice and should not be relied on as such. It is not a solicitation to buy or an offer to sell any security. It does not take into account any individual's particular investment objectives, financial situation, or needs. You should consult your own financial advisor, tax advisor, or attorney before acting on any information herein. All investing involves risk, including the possible loss of principal. Figures and tax limits referenced are for the applicable tax year and are subject to change. Valence Wealth, LLC is a registered investment advisor in the State of Arizona. Registration does not imply any specific level of skill or training. Valence Wealth is not affiliated with, endorsed by, or sponsored by Meta Platforms, Inc., Alphabet Inc., Intel Corporation, Amazon.com, Inc. or any exchange fund sponsor. Trading policy terms are summarized from the companies' public filings as of the date of publication. They can change at any time. References to employer stock describe how the tax rules work and are not a recommendation to buy, sell or hold any security. References to exchange funds describe how they generally work and are not a recommendation of any exchange fund. Valence Wealth, its owner and its clients may hold positions in these companies' stock. Hypothetical examples are not actual results or forecasts.
Sources
- 26 U.S. Code 402: taxability of beneficiary of employees' trust (net unrealized appreciation, lump-sum distribution)Cornell Legal Information Institute
- 26 U.S. Code 401: qualified pension, profit-sharing and stock bonus plans (cash or deferred arrangements)Cornell Legal Information Institute
- 26 CFR 1.402(a)-1: taxability of beneficiary under a trust which meets the requirements of section 401(a)Cornell Legal Information Institute
- IRS Notice 98-24: net unrealized appreciation in employer securitiesInternal Revenue Service
- IRS Publication 575 (2025): pension and annuity income (distributions of employer securities, lump-sum distributions, tax on early distributions)Internal Revenue Service
- IRS Notice 2026-13: safe harbor explanations, eligible rollover distributionsInternal Revenue Service
- 26 CFR 1.1411-8: exception for distributions from qualified plansCornell Legal Information Institute
- Instructions for Form 8960: net investment income taxInternal Revenue Service
- 26 CFR 31.3405(c)-1: withholding on eligible rollover distributionsCornell Legal Information Institute
- 26 U.S. Code 72: annuities (10% additional tax on early distributions)Cornell Legal Information Institute
- 26 U.S. Code 408: individual retirement accountsCornell Legal Information Institute
- IRS Publication 590-B: distributions from individual retirement arrangementsInternal Revenue Service
- 26 U.S. Code 721: nonrecognition of gain or loss on contributionCornell Legal Information Institute
- 26 U.S. Code 722: basis of contributing partner's interestCornell Legal Information Institute
- 26 CFR 1.351-1: transfer to corporation controlled by transferor (investment company transfers)Cornell Legal Information Institute
- 26 U.S. Code 704: partner's distributive share (contributed property distributed within 7 years)Cornell Legal Information Institute
- 26 U.S. Code 737: recognition of precontribution gain in case of certain distributions to contributing partnerCornell Legal Information Institute
- 26 U.S. Code 732: basis of distributed property other than moneyCornell Legal Information Institute
- 26 U.S. Code 731: extent of recognition of gain or loss on distribution (marketable securities treated as money)Cornell Legal Information Institute
- 26 U.S. Code 1223: holding period of propertyCornell Legal Information Institute
- 26 U.S. Code 735: character of gain or loss on disposition of distributed property (holding period)Cornell Legal Information Institute
- IRS Publication 541: partnershipsInternal Revenue Service
- 26 U.S. Code 702: income and credits of partnerCornell Legal Information Institute
- Partner's Instructions for Schedule K-1 (Form 1065)Internal Revenue Service
- 26 U.S. Code 1014: basis of property acquired from a decedentCornell Legal Information Institute
- Rev. Rul. 75-125, 1975-1 C.B. 254 (NUA as income in respect of a decedent)Internal Revenue Service ruling, reproduced by Bradford Tax Institute
- IRS Publication 551: basis of assets (inherited property)Internal Revenue Service
- Revenue Procedure 2025-32: 2026 inflation adjustmentsInternal Revenue Service
- IRS Topic 409: capital gains and lossesInternal Revenue Service
- 17 CFR 230.501: definitions and terms used in Regulation D (accredited investor)Cornell Legal Information Institute
- SEC: accredited investorsU.S. Securities and Exchange Commission
- 15 U.S. Code 80a-2: definitions (qualified purchaser)Cornell Legal Information Institute
- SEC small business glossary (qualified purchaser)U.S. Securities and Exchange Commission
- 17 CFR 229.407: corporate governance (Item 407(i), employee, officer and director hedging)Cornell Legal Information Institute
- SEC Release No. 33-10593: disclosure of hedging by employees, officers and directorsU.S. Securities and Exchange Commission
- Meta Platforms Insider Trading Policy (Exhibit 19.1 to the 2024 Form 10-K)Meta Platforms, Inc., filed with the SEC
- Meta Platforms 2026 Proxy Statement (hedging)Meta Platforms, Inc., filed with the SEC
- Alphabet 2024 Proxy Statement (insider trading, hedging and pledging policies)Alphabet Inc., filed with the SEC
- Alphabet 2023 Proxy Statement (insider trading, hedging and pledging policies)Alphabet Inc., filed with the SEC
- Alphabet Policy Against Insider Trading (Exhibit 19.01 to the 2024 Form 10-K)Alphabet Inc., filed with the SEC
- Intel Insider Trading Policy (Exhibit 19.1 to the fiscal 2025 Form 10-K)Intel Corporation, filed with the SEC
- Intel Insider Trading Policy (Exhibit 19.1 to the fiscal 2024 Form 10-K)Intel Corporation, filed with the SEC
- Amazon.com Insider Trading Policy (Exhibit 19.1 to the 2024 Form 10-K)Amazon.com, Inc., filed with the SEC
- Amazon.com 2026 Proxy Statement (anti-hedging policy)Amazon.com, Inc., filed with the SEC
- S.2095, PARTNERSHIPS Act, 119th Congress, as introduced (section 14)U.S. Government Publishing Office
- S.2095 bill statusU.S. Government Publishing Office
- Senate Finance Committee: PARTNERSHIPS Act section-by-section summary (section 14, swap funds)U.S. Senate Committee on Finance