Executive Summary
- Indexed universal life (IUL) is permanent life insurance with a cash value that earns interest based on a stock index, within a cap and a floor that's often 0%. Your premiums go into the insurer's general account and aren't invested in the index or in any stocks.
- The tax-free retirement income in IUL sales pitches generally comes from policy loans. Borrowing against a brokerage account isn't taxable income either, and both kinds of loan charge interest. If the policy lapses or is surrendered with a loan outstanding, the gain is generally taxed as ordinary income, even if you receive no cash.
- The insurer, not you, sets the cap and participation rate that limit your index credit, and it can lower them after you buy, down to the minimums in the contract.
- Index credits leave out dividends. Over the 10 years to October 30, 2026, the S&P 500 total return was 15.44% a year, but if you remove dividends it drops to 13.56% a year.
- The 0% floor applies to the index credit, not to your account. The cost of insurance and other charges come out every month, so the cash value can fall in a year credited at 0%.
- Universal life commissions are highest in the first policy year, paid as a percentage of a target premium that generally rises with the death benefit, so a bigger policy pays a bigger commission.
How IUL works
You've maxed out your 401(k), your RSUs keep vesting, and taxes are one of the biggest lines in your budget. Then someone offers what sounds like the fix. It's a life insurance policy that grows with the stock market, can't lose money in a down year and pays you tax-free income in retirement. The product is indexed universal life insurance, or IUL, and it sells. IUL brought in $4.5 billion of new premium in 2025, about a quarter of all new individual life insurance premium in the US.
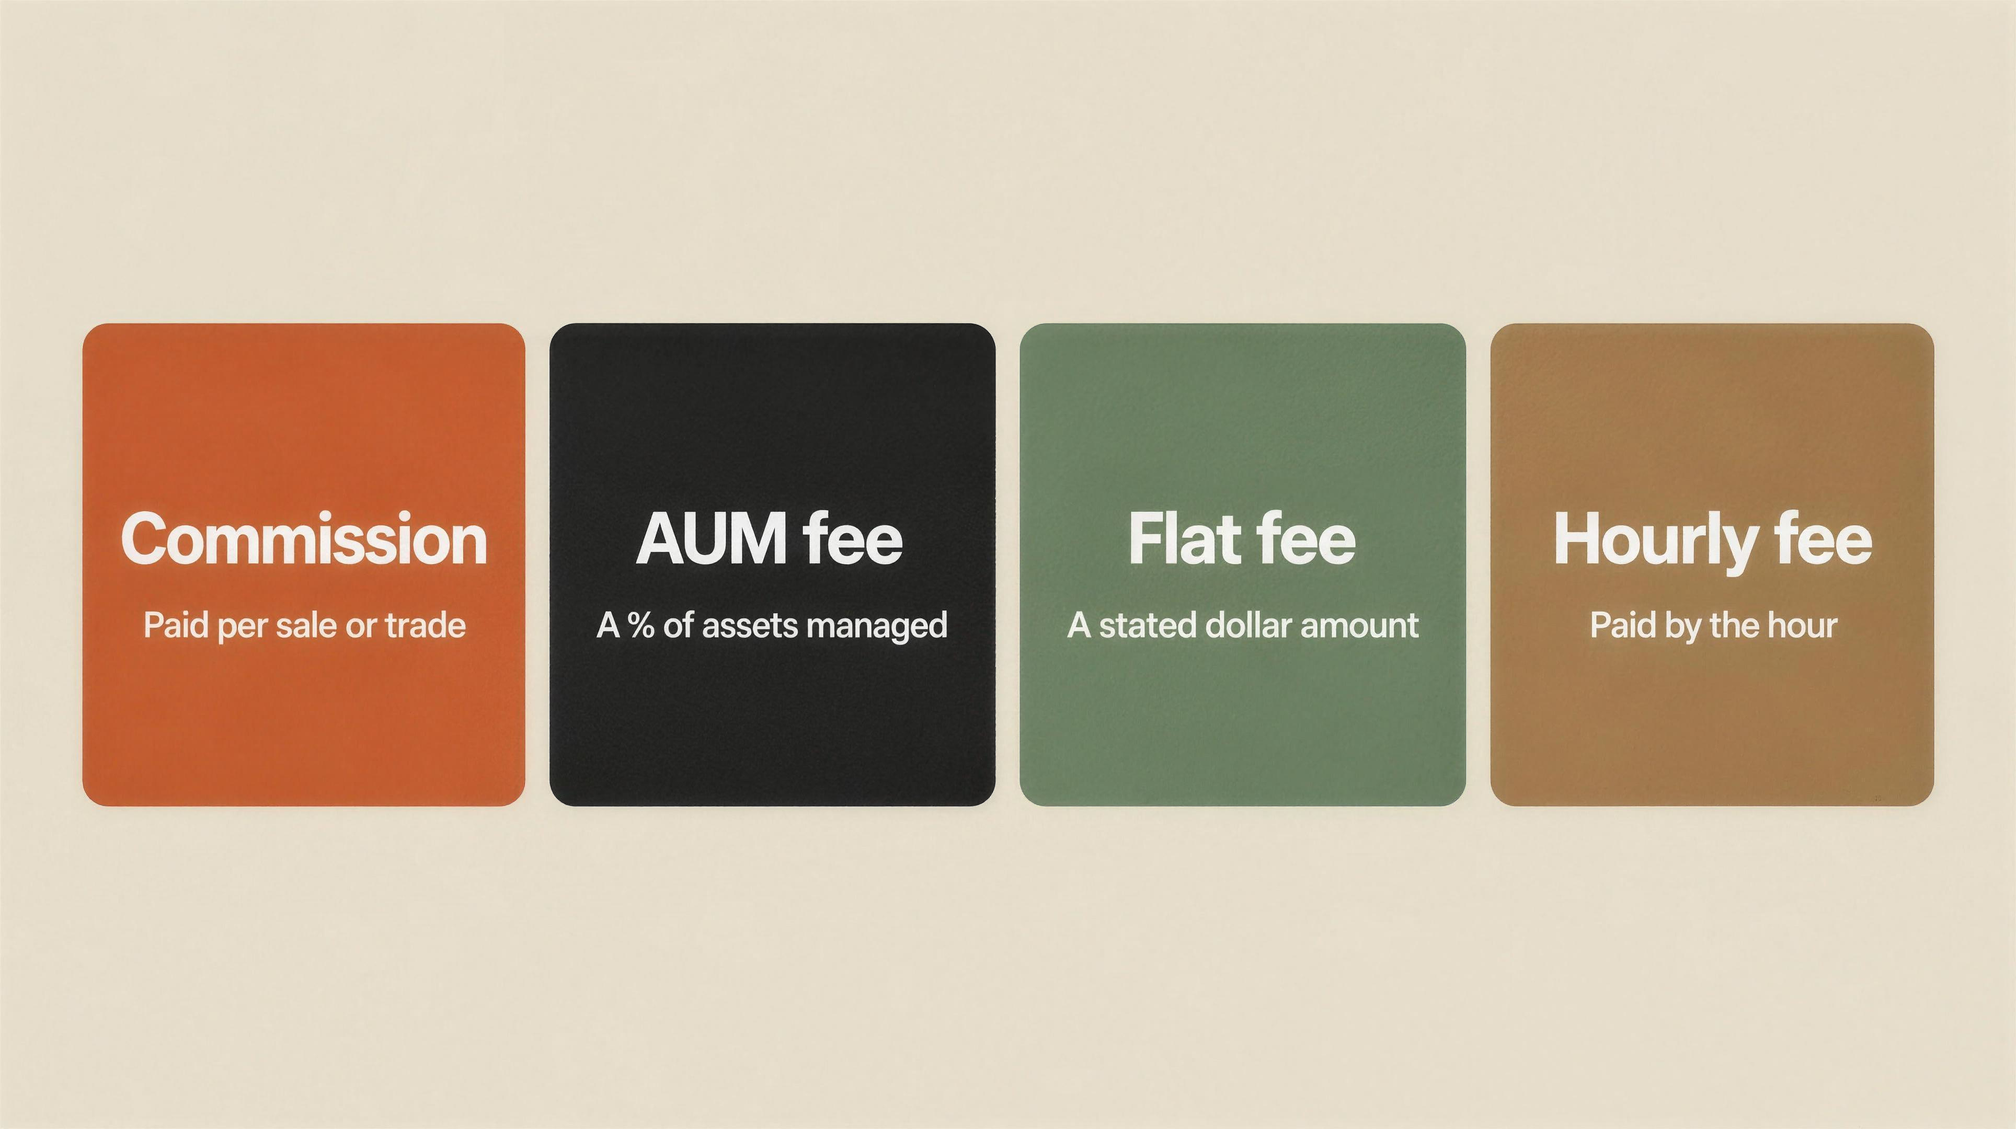
I regularly hear from people who bought an IUL and now want a second opinion on it. This article explains what sits under the pitch, so you can judge a policy before you buy one or decide what to do with one you already own. Valence Wealth charges a flat fee and earns no commissions, so I'm not paid more or less based on what you buy.
IUL is permanent life insurance with a cash account inside it. Each premium goes into the account after the insurer takes its premium charges. Every month the insurer deducts the cost of insurance and other policy charges. At the end of each crediting period, often a year, the account earns an index credit based on the change in a stock index such as the S&P 500, within limits the insurer sets. When you die, your beneficiaries receive the death benefit, minus any loans.
The index credit is where the pitch lives. If the index rises, you're credited part of the rise, up to a cap. If it falls, there is a floor on your credit, often 0%.
An IUL isn't an investment account. Your premiums aren't invested in the index or in any stocks. They go into the insurer's general account, the assets the insurer owns and invests to pay its claims and run its business. None of those assets belong to any one policyholder. Your cash value is a balance the insurer credits to you under the contract. To pay for index credits, the insurer buys options on the index with part of what its general account earns. An option on the index doesn't hold the stocks in it, so it doesn't collect their dividends, and thus neither does your policy.
| Part | What it does | Can it change after you buy? |
|---|---|---|
| Cap | The most you can be credited in a period | Yes, down to the contract minimum |
| Participation rate | The % share of the index gain you're credited | Yes, down to the contract minimum |
| Spread | A cut taken from the index gain on some accounts | Yes, up to the contract maximum |
| Floor | The least you can be credited, often 0% | No, it's set in the contract |
| Premium charges | A percentage taken from each premium | Yes, up to the contract maximum |
| Cost of insurance | A monthly charge for the death benefit that rises with age | Yes, up to the contract maximum |
| Other monthly charges | Policy fees and charges per $1,000 of coverage | Yes, up to the contract maximum |
| Surrender charge | A charge if you cash out in the early years | No, it's set in the contract |
| Loan rate | Interest on what you borrow | Yes, up to the contract maximum |
1. Too many moving parts
As you can see, these are very complex financial products. Most lines in that table can move independently, and often they're controlled by the insurance company - not the policyholder. A lower cap, a cost of insurance increase later in life or a few years of 0% credits can decide whether a policy lasts to age 100 or runs out of money decades earlier. You'd only see that by rerunning the numbers under different assumptions. New York's insurance regulator offers blunt advice in its consumer alert on universal life. If you don't understand the policy, don't buy it.
The sales illustrations have needed repeated fixes too. Regulators adopted Actuarial Guideline 49 for IULs sold from September 1, 2015, to limit how high an illustration's assumed rate could go. In 2020 they barred illustrations from showing extra growth from bonuses and multipliers and lowered the limit on illustrated loan gains. They revised the rules again for policies sold from May 1, 2023, and again for policies sold from April 1, 2026. Four rounds of rules in about 11 years show how hard these policies are to judge from a sales illustration.
2. "Tax-free income" is a loan
The headline benefit in most IUL pitches is tax-free retirement income. That income generally comes out in two steps. First, you withdraw up to what you've paid in premiums (your basis), which generally isn't taxed in a policy that isn't a modified endowment contract, or MEC. After that, you borrow against the cash value. A policy loan isn't taxed while the policy stays in force, because borrowed money isn't income.
That's the same reason a loan against a brokerage account isn't taxed. A securities-based line of credit (SBLOC) or a margin loan lets you borrow against an investment account, and the proceeds aren't income either. The endings line up as well. When you die, a policy loan is repaid out of the death benefit, which is generally income-tax-free. A brokerage account generally gets a step-up in basis at death, so it can be sold to repay the loan with little or no capital gains tax.
The differences cut both ways. A brokerage lender can demand more collateral or sell your holdings when markets fall, and SBLOC rates usually float. A policy loan has no margin call, but if the loan grows faster than the cash value, the policy can lapse unless you pay in more, and leave you with a tax bill (section 7). Interest on either loan is generally not deductible when you spend the money on living costs.
| Feature | Policy loan | SBLOC or margin loan |
|---|---|---|
| Collateral | The policy's cash value | Your investment account |
| Tax when you borrow | None, if the policy isn't a MEC and stays in force | None |
| Interest | Set by the insurer and added to the loan unless you pay it | Set by the lender, often a floating rate |
| If values fall | The policy can lapse and the gain is taxed | The lender can demand collateral or sell holdings |
| At death | Repaid from the death benefit | Repaid from an account that generally gets a step-up in basis |
3. The insurer sets your upside
Two rates decide how much of an index gain reaches your cash value, and the insurer sets both.
- Cap. The most you can be credited in a period. If the index's price rises 20% in a year and your cap is 10%, you're credited 10%.
- Participation rate. The % share of the index gain you're credited. At a 50% participation rate, the same 20% rise credits 10%.
Some accounts take a spread instead, a cut from the index gain before you're credited.
You don't choose these rates, and they aren't fixed for the life of the policy. The insurer sets them for each crediting period and can lower caps and participation rates after you buy, down to the minimums in the contract. How high they can go depends on the insurer's option budget, which comes from what its general account earns. So the insurer can throttle your credits. A cap shown in your sales illustration isn't guaranteed for later years.
4. Index credits leave out dividends
This one is big. An IUL credit tracks the index's price, not its total return. The dividends paid by the companies in the S&P 500 aren't included in the cash value. Over the 10 years to October 30, 2026, the S&P 500 total return was 15.44% a year with dividends reinvested, but if you remove dividends it drops to 13.56% a year. On $100,000 over those 10 years, that would have been the difference between about $420,000 and about $357,000. Over the index's longer history, S&P Dow Jones Indices puts dividends at roughly a third of its total return.
What you get in return for missing the dividends and accepting a cap is the floor, which means no negative credit in a down year. That has value. A mix of stocks and bonds also cushions down years, keeps the dividends and carries no insurance charges, though stocks and bonds can both lose value.
5. Charges don't stop at the floor
The 0% floor applies to the index credit, not to your account. The cost of insurance, policy fees and other charges come out every month whether the index rose or fell. In a 0% year, your cash value drops whenever those charges are bigger than the premium you paid in.
Say your cash value is $300,000, you've stopped paying premiums and the index falls, so you're credited 0%. If this year's charges total $6,000, your cash value ends the year at $294,000. The floor didn't stop the account from falling.
The cost of insurance rises as you age, and insurers can raise their cost of insurance rates up to the maximums in the contract. Some have done it on existing universal life policies, and class actions followed. Equitable, formerly AXA Equitable, settled one over its cost of insurance increases while denying the claims, approved in 2023.
6. Commissions reward a bigger policy
IUL is sold by licensed insurance agents, and the insurer generally pays them commissions. Universal life commissions can be high, and they're front-loaded. The highest rate is paid in the first policy year, as a percentage of a target premium, and the rate drops sharply after that.
Insurers don't have to publish IUL commission schedules. Variable universal life (VUL), a close cousin sold by prospectus, does. VUL schedules filed with the SEC between 2008 and 2024 show maximum first-year commissions from 42.5% to 115% of the target premium, and 1.5% to 20% in later years.
The target premium generally rises with the death benefit, so a bigger policy pays a bigger commission. There's nothing wrong with people making money. But the incentive is to sell you the biggest policy possible.
As a general rule, courts have held that an insurance agent has no continuing duty to monitor or advise you after the sale unless there's a special relationship, though the rules vary by state.
Sales rules are lighter too. IUL isn't registered with the SEC as a security, unlike variable universal life. New York is the only state we found that applies a best-interest standard to life insurance sales.
7. A lapse can bring a tax bill and no cash
Policy loans stay tax-free only while the policy stays in force. If the loan and its interest grow until they use up the cash value, the policy lapses unless you pay in more. When that happens, the cash value pays off the loan and the tax code treats it as money you received. Everything above your basis is taxed as ordinary income that year, even if you don't get a check.
Say you paid $400,000 in premiums, the cash value grew to $700,000, and you borrowed until the loan and its interest reached $700,000, the whole cash value. If the policy lapses, you receive nothing and report $300,000 of ordinary income. Federal appeals courts have upheld this tax in cases where the owner received no cash. Because loans build up over years, the risk grows the longer you borrow.
Paying in too much too fast causes a different problem. A policy that fails the tax code's seven-pay test becomes a modified endowment contract (MEC). Its loans and withdrawals are taxed gain-first, plus a 10% additional tax before age 59½ unless an exception applies. That's one reason an IUL can't take unlimited money and pay it back out tax-free.
8. Illustrations aren't projections
An IUL sale usually comes with an illustration, a year-by-year table showing the cash value growing at an assumed rate for decades. That rate isn't guaranteed. Under the current rules, it's based on how the S&P 500 would have done over rolling 25-year periods at today's cap, and it's limited by the insurer's investment earnings.
Read the guaranteed column first. It shows what the insurer promises at its maximum charges and minimum credits. Then ask for the same illustration at a lower assumed rate, say two points below the one you were shown. If the policy only works at the full assumed rate, the plan is fragile.
Where IUL can fit
IUL can make sense for a narrow group of people with a lasting need for a death benefit, such as estate liquidity or a dependent who'll need support for life, who've already used their tax-advantaged accounts and can fund a policy heavily for decades. Even then, compare it with other types of permanent life insurance before choosing.
For most tech employees, the problems IUL is pitched to solve have simpler tools.
- Protecting your family's income. Term life insurance covers the years when people depend on your paycheck.
- More tax-advantaged savings. If your 401(k) allows after-tax contributions and Roth conversions, the mega backdoor Roth lets you save beyond the regular deferral limit. A health savings account, if you're eligible, is another option.
- Investing in a taxable account. Broad index funds or direct indexing keep the dividends and carry no insurance charges. They have their own fees, you generally pay tax on dividends and on gains as you realize them, and they can lose value.
Already own one?
If you bought an IUL and now have doubts, don't cancel it in a hurry. Surrender charges, loans, your health and your basis all change the math, and coverage you drop can be harder to replace as you get older.
- Get an in-force illustration. Ask the insurer to run your policy at its current assumptions, at a lower assumed rate and at the guaranteed values. It shows how long the policy lasts if nothing changes.
- Find your surrender value. Compare the cash value with the surrender value on your latest statement. If you have no loan, the difference is the surrender charge, which typically shrinks each year until it's gone.
- Check the loans. Find the balance, the rate and whether it's a fixed or a variable (indexed) loan.
- Line up new coverage first. If someone depends on you, get approved for replacement coverage, often term insurance, before you drop the old policy.
- Compare your options. You can keep funding the policy, lower the death benefit to cut the cost of insurance, exchange it tax-free for another policy or an annuity under Section 1035, or surrender it. A surrender is taxed on any gain above your basis. Lowering the death benefit in the first 15 years, or exchanging a policy with a loan on it, can also create tax, so have a tax professional check the numbers first.
This is general education, not a recommendation about any policy. Whether a policy fits depends on your need for coverage, your health, how it's funded, your taxes, your goals and the terms of the contract you own. Features, charges and loan terms vary by insurer and product. The dollar figures are hypothetical illustrations, not projections or results. Index returns don't reflect fees or insurance charges, and you can't invest directly in an index. Tax law can change.
Disclosures: The information provided is for educational and informational purposes only and does not constitute investment, tax, or legal advice and should not be relied on as such. It is not a solicitation to buy or an offer to sell any security. It does not take into account any individual's particular investment objectives, financial situation, or needs. You should consult your own financial advisor, tax advisor, or attorney before acting on any information herein. All investing involves risk, including the possible loss of principal. Figures and tax limits referenced are for the applicable tax year and are subject to change. Valence Wealth, LLC is a registered investment advisor in the State of Arizona. Registration does not imply any specific level of skill or training. Valence Wealth earns no commissions and is not affiliated with, endorsed by, or sponsored by any company named in this article. References to insurance products describe how they generally work and are not a recommendation to buy, keep, exchange or surrender any policy. Index figures are from S&P Dow Jones Indices. Past performance is not indicative of future results. Hypothetical examples are not actual results or forecasts.
Sources
- LIMRA: double-digit growth drives individual life insurance new premium to set new sales record in 2025 (March 3, 2026)LIMRA
- Federal Insurance Office Annual Report on the Insurance Industry (September 2026)U.S. Department of the Treasury
- Understanding Indexed Universal Life Insurance (form 295NM-A, 4/18)North American Company for Life and Health Insurance
- Actuarial Guideline XLIX-A: the application of the Life Illustrations Model Regulation to policies with index-based interest sold on or after December 14, 2020 (as revised)National Association of Insurance Commissioners
- Actuarial Guideline XLIX (as revised December 2016)National Association of Insurance Commissioners
- Product Matters!, IUL illustrations and option budgets (June 2023)Society of Actuaries
- NAIC Executive and Plenary adoption record for the 2023 AG 49-A revisions (March 2023)National Association of Insurance Commissioners
- AG 49-A revisions for policies sold on or after April 1, 2026 (Regulatory Roundup)Lincoln Financial
- Life insurance illustrations (topic page, updated January 8, 2026)National Association of Insurance Commissioners
- DFS consumer alert on universal life insurance (February 21, 2019)New York State Department of Financial Services
- Consumer alert: universal life insurance (December 3, 2021)Wisconsin Office of the Commissioner of Insurance
- Life Insurance Buyer's GuideNational Association of Insurance Commissioners
- Universal Life Insurance Model Regulation (#585)National Association of Insurance Commissioners
- Horace Mann Educators 2018 audited financial statements (index-linked products and call options)filed with the Wisconsin Office of the Commissioner of Insurance
- 26 U.S. Code 72: annuities, certain proceeds of endowment and life insurance contractsCornell Legal Information Institute
- Rev. Proc. 2008-39 (modified endowment contracts)Internal Revenue Service
- Rev. Rul. 2009-13 (surrender of a life insurance contract)Internal Revenue Service
- 26 U.S. Code 7702A: modified endowment contract definedCornell Legal Information Institute
- 26 U.S. Code 101: certain death benefitsCornell Legal Information Institute
- IRS Publication 525: taxable and nontaxable income (life insurance proceeds)Internal Revenue Service
- 26 U.S. Code 1014: basis of property acquired from a decedentCornell Legal Information Institute
- IRS Publication 551: basis of assets (inherited property)Internal Revenue Service
- Commissioner v. Tufts, 461 U.S. 300 (1983)U.S. Supreme Court, via the Library of Congress
- Commissioner v. Indianapolis Power & Light Co., 493 U.S. 203 (1990)U.S. Supreme Court, via the Library of Congress
- Investor Bulletin: Understanding Margin Accounts (June 10, 2021)U.S. Securities and Exchange Commission, Office of Investor Education and Advocacy
- Investor Alert: Securities-Backed Lines of Credit (December 21, 2015)U.S. Securities and Exchange Commission, Office of Investor Education and Advocacy
- IRS Publication 550: investment income and expenses (interest expenses, insurance policies)Internal Revenue Service
- 26 U.S. Code 163: interest (personal interest)Cornell Legal Information Institute
- S&P 500 index performance (as of October 30, 2026)S&P Dow Jones Indices
- A Fundamental Look at S&P 500 Dividend Aristocrats (March 19, 2025)S&P Dow Jones Indices
- The Importance of Dividends (November 17, 2025)S&P Dow Jones Indices
- Brach Family Foundation, Inc. v. AXA Equitable Life Insurance Company, No. 1:16-cv-00740 (S.D.N.Y.), official settlement websiteSettlement Administrator
- Equitable Holdings Form 10-Q, quarter ended September 30, 2024 (cost of insurance litigation)filed with the SEC
- Life insurance (consumer page, surrender periods)New York State Department of Financial Services
- Protective Life Insurance Company Form 10-K for 2018 (target premium)filed with the SEC
- American Family Variable Universal Life II prospectus (December 1, 2008)filed with the SEC
- Northwestern Mutual Variable Universal Life Plus prospectus (November 11, 2019)filed with the SEC
- Phoenix Life Flex Edge variable universal life registration statement (April 2012)filed with the SEC
- New York Life VUL Accumulator Plus registration statement (December 20, 2024)filed with the SEC
- Murphy v. Kuhn, 90 N.Y.2d 266 (1997)New York Court of Appeals, via Cornell Legal Information Institute
- Harts v. Farmers Insurance Exchange, 461 Mich. 1 (1999)Michigan Supreme Court, via CaseMine
- 15 U.S. Code 77c: exempted securities (insurance policies)Cornell Legal Information Institute
- SEC Release No. 33-10765: updated disclosure requirements for variable annuities and variable life insurance contracts (2020)U.S. Securities and Exchange Commission
- Regulation 187 filings guidanceNew York State Department of Financial Services
- 11 NYCRR 224.4: best interest standardCornell Legal Information Institute
- Brown v. Commissioner, 693 F.3d 765 (7th Cir. 2012)U.S. Court of Appeals for the Seventh Circuit, via govinfo
- McGowen v. Commissioner, 438 F. App'x 686 (10th Cir. 2011)U.S. Court of Appeals for the Tenth Circuit, via govinfo
- Life Insurance Illustrations Model Regulation (#582)National Association of Insurance Commissioners
- A.R.S. 20-431.04: life insurance illustrations, basic illustrationArizona State Legislature
- 26 U.S. Code 7702: life insurance contract defined (benefit reductions in the first 15 years)Cornell Legal Information Institute
- 26 U.S. Code 1035: certain exchanges of insurance policiesCornell Legal Information Institute
- Instructions for Forms 1099-R and 5498 (2026), section 1035 exchangesInternal Revenue Service